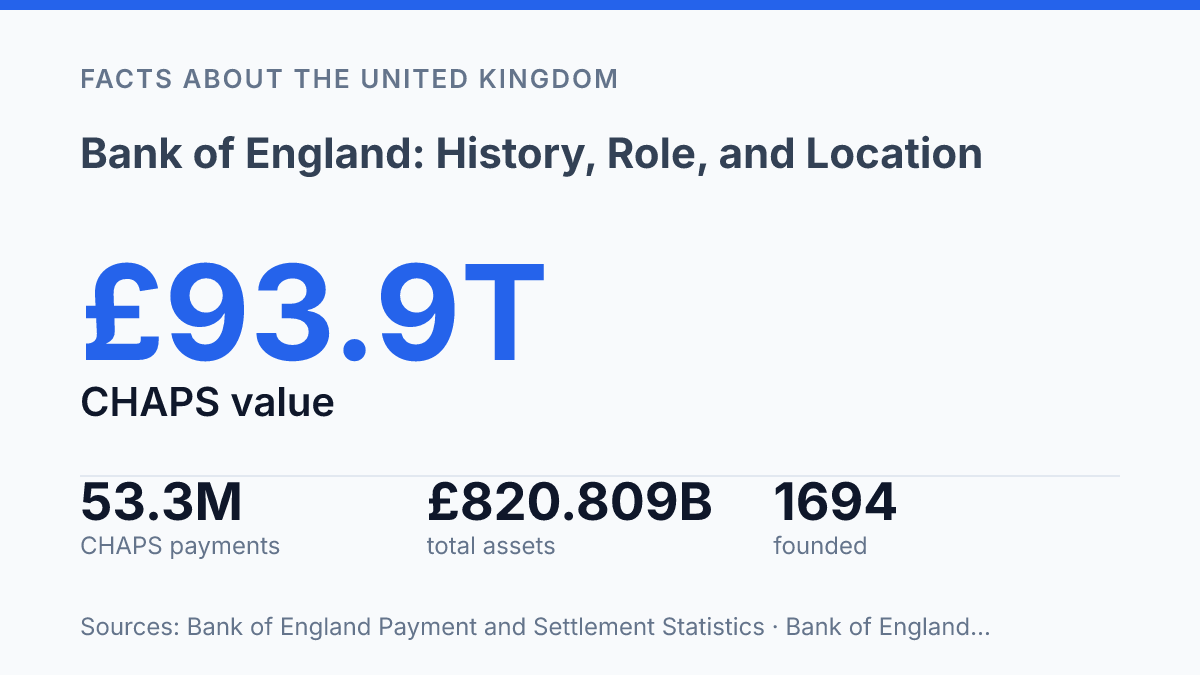
The Bank of England began as a £1.2 million loan to the government in 1694, subscribed by 1,520 named investors ranging from £25 contributors to King William and Queen Mary at £10,000. That origin still matters because the institution’s modern authority rests on a rare blend of public finance, legal privilege, and operational scale. The remaining historic balance from the founding loan was not cleared until July 1994, while its 2026 annual accounts recorded £820.809 billion in combined assets.
Between those dates sit the reforms that made it a model for central banking, including the 1844 separation of note issue from banking. The article traces that arc from foundation to present function: how the Bank became embedded in the British state, what it now does through monetary policy and payment systems, why its structure influenced later central banks, and how its Threadneedle Street base still anchors its public role.
How the central bank was founded in 1694
A private subscription of £1.2 million turned an urgent wartime borrowing problem into one of the most durable models in public finance. According to the Bank of England Archive, the 1694 launch subscription drew 1,520 separate names, with contributions ranging from £25 to £10,000 from King William and Queen Mary. The scale and speed of that fundraising mattered because the government needed dependable credit during war with France, when conventional revenue and borrowing channels were under severe strain.
The institution was founded on July 27, 1694, at Walbrook, London, with Charles Montagu, 1st Earl of Halifax, central to its creation in his role as a leading political and financial architect of the scheme. Its founding arrangement was direct: subscribers supplied capital, the new corporation lent the money to the government, and the state paid interest in return. The Bank’s own historical account notes that the 1694 loan carried 8% interest, showing that the original design was not an abstract monetary project but a practical mechanism for public finance.
That wartime origin shaped the institution’s later significance. It began as a joint-stock corporation serving the fiscal needs of the state, yet the model linked private capital, government credit, and public authority in a way that later central banks would adapt. The early mandate did not resemble the full range of modern monetary responsibilities, but it established a durable principle: a central financial institution could strengthen sovereign borrowing capacity while gradually acquiring wider importance in the management of money, credit, and confidence.
What the Bank of England does today
CHAPS processed a record 53.3 million payments worth £93.9 trillion in 2025, a scale that shows how much of the United Kingdom’s financial plumbing depends on central-bank infrastructure, according to Bank of England Payment and Settlement Statistics. Although those payments represented only 0.4% of UK payment volumes, they accounted for 91% of sterling payment values, making the system especially significant for wholesale finance, house purchases, government transactions, and major corporate transfers.
The Bank of England is the United Kingdom’s central bank and is responsible for monetary stability, which means keeping inflation low and stable while supporting confidence in money. Its most visible policy tool is Bank Rate, set by the Monetary Policy Committee. At the MPC meeting ending 16 September 2026, members voted 6–3 to hold Bank Rate at 3.75%, according to the Monetary Policy Summary, illustrating that rate decisions are formal committee judgments rather than ministerial announcements.
Currency is another core public function. The bank issues banknotes in England and Wales and manages the integrity of those notes as part of the wider sterling currency system. The Bank Charter Act 1844 gave it a monopoly of note issue in England and Wales and created separate Banking and Issue Departments, a structural distinction the institution says is still maintained today.
Financial stability work sits alongside monetary policy. The bank monitors risks across banks, markets, payment systems, and the broader financial system, with oversight aimed at reducing the chance that stress in one part of finance spreads into the wider economy. Its influence is therefore broad, but not unlimited: policy decisions are shaped by inflation data, credit conditions, market functioning, and the need to preserve public confidence in sterling and the financial system.
Why it became the model for modern central banks
By 1900, only 17 central banks existed worldwide, and just two had been founded before 1700: Sweden’s Riksbank and the institution created in Britain in 1694. That longevity gave the British model unusual authority because it showed that a central bank could survive changes in government, war finance, industrialisation, financial crises, and shifts from metallic money to modern monetary management. Its influence rested less on a single legal template than on a durable institutional idea: monetary authority could be concentrated in a specialist public institution with a close, but not identical, relationship to the state and the banking system.
The founding mechanism also mattered because it connected public finance with private capital at a scale that was unusual for the period. According to the Bank of England Archive, the 1694 launch subscription raised £1,200,000 for the government, with 1,520 separate names contributing from £25 up to £10,000 from King William and Queen Mary. That arrangement helped establish a pattern later seen in different forms elsewhere: a central monetary institution could support sovereign finance while developing functions that extended beyond ordinary commercial banking.
Later central banks in Europe, North America, and other major economies drew from this precedent, but they were not simple copies. The Federal Reserve, created in 1913, was designed for a federal political system and therefore combined a central board with regional reserve banks.
The European Central Bank, established for a monetary union rather than a single nation-state, exercises authority over a shared currency used by multiple member countries. Both examples show how the central-bank model adapted to different constitutional settings while preserving core features: monetary-policy authority, lender-of-last-resort capacity, banking-system oversight, and operational distance from day-to-day political pressure.
Independence is the clearest comparison point. The British institution became a reference model because it demonstrated that monetary credibility depends on stable mandates, technical expertise, and continuity across political cycles.
Later institutions formalised those principles in different ways, often through statutory objectives, committee-based decisions, and protections from direct government instruction. Its prototype status therefore reflects influence rather than uniform replication: modern central banks inherited the broad architecture of specialised monetary authority, then reshaped it around their own economies, legal systems, and political constraints.
Where it is based and how to contact it
A single street address in the City of London serves as the practical point of reference for an institution whose decisions operate across the United Kingdom. Its address is Threadneedle St, London EC2R 8AH, United Kingdom, placing it in the financial core of the capital while its responsibilities remain national in scope. The location is useful for identification, correspondence, and institutional reference, but it should not be read as limiting the bank’s role to London or to the surrounding financial district.
For general enquiries, the main contact number is +44 20 3461 4444. According to the institution’s 2026 contact page, its main switchboard is open Monday to Friday, 9am to 5pm, which makes this the appropriate first point of contact for routine public enquiries rather than specialist regulatory or policy matters. The combination of a precise City address and a central switchboard reflects the bank’s dual character: physically rooted in one of London’s oldest financial areas, yet operating as a major national institution within the UK’s monetary and financial system.
Why Threadneedle Street still matters
The practical significance of Threadneedle Street is not just that it gives the institution a fixed address. It makes a highly technical authority visible: a place where monetary policy decisions, banknote responsibilities, financial-stability work, and wholesale payment infrastructure can be traced to a public body with statutory duties. That visibility matters more as central banking becomes less tangible, with most money moving through ledgers and settlement systems rather than notes.
CHAPS data from 2025 shows the scale clearly: a small share of payment volume carried 91% of sterling payment value. For researchers, businesses, and members of the public, the address, switchboard, and published decisions are part of the same accountability framework.
Frequently Asked Questions
Q: What does the Bank of England do?
A: The Bank of England is the central bank of the United Kingdom. It helps set monetary policy, supports financial stability, and oversees currency issuance. Its role makes it the main institution behind the UK’s monetary system.
Q: Where is the Bank of England located?
A: Its main address is Threadneedle St, London EC2R 8AH, United Kingdom. The institution is based in the City of London, close to the centre of the UK’s financial district. This location reflects its long-standing role in national finance.
Q: When was the Bank of England founded?
A: It was founded on July 27, 1694, in Walbrook. The bank was created during a period of major government financing needs, which shaped its early purpose. That founding date places it among the oldest central banks in continuous operation.
Q: Who founded the Bank of England?
A: The bank was founded by Charles Montagu, 1st Earl of Halifax. He played a central role in establishing the institution in 1694. That origin is important because it links the bank’s creation to the financial needs of the state.
Q: How can someone contact the Bank of England?
A: The main contact number is +44 20 3461 4444. This is the primary phone line for reaching the institution. For location-specific enquiries, the official London address is also listed publicly.